PUBLICATION
Turnarounds with lean management
It was with great optimism and expectations that Bridgeport USA and Texmaco, South East Asia came together to set up a joint venture for CNC and conventional machines, but sometimes, even the best laid plans can go awry, as happened in this case. Here’s an in depth view at how establishing lean practices throughout the organization led to a complete turnaround in overall performance and achievements.
It seemed like a blueprint for success when some years ago, a joint venture was embarked upon by Bridgeport USA and Texmaco, South East Asia, with a view to build CNC machining centers, CNC and conventional milling machines in Indonesia. This set up was one of Texmaco’s business verticals in its engineering business sector and its second one in machine tools. The ambitious project was headed by seeded experts, including an ex-chairman of one of the world’s largest machine tool company and the multicultural team comprised American, British, Chinese, Singaporean and Indian members. The land, building and manpower were supplied by the local partner while engineers and workmen were trained at the collaborator’s factory in the US. And to crown it all, the local company had a foundry within the group, and the plan was to supply castings from within.
But five years down the line, with everything in place, teams and machines both working and incurring costs, a single machine was yet to be produced by the company.
Identifying the central problem
In five years, some castings were developed and some machining was done but it was never converted into a complete machine. Internal discussions revealed that the business process was not well-defined and diverse views between the marketing and operational departments were essentially creating a block. There was a value stream with nothing flowing and the thinking was topsy-turvy and discrete. We asked ourselves: What processes were going wrong? What could be done to change this situation? We then came upon a solution and in this article, out of the various products manufactured, the milling machine has been used as a reference example to explain the case.
The main issues
The factors that were identified as playing a role in the company not being able to produce any machines were:
- No clear authority in place, although people with roles were in place
- Indonesia was and is not a name known for machine tool production in the global market
- Focus on the product market matrix and price point for market entry was missing as was an evaluation of correct market scenes. Although the company was supported by technical knowhow from the parent company, a proper buy back arrangement was missing, thereby both sides were losing out on potential opportunities.
- Target markets were not clearly identified, although everybody knew that there was a market for such machines
- Core competencies required to build this business were not identified. A good business process, sound philosophy and proper perspective were wanting.
- The pricing factor had probably killed the project. There was total disconnection between expectation and reality. For example: the thinking that prevailed was that we were expected to sell a milling machine at $10,000 per piece, while Taiwan sold them for approximately $2,400-2,600 a piece. While Taiwan sold about 35,000 machines a year, Bridgeport’s numbers were at best in triple digits.
- The casting factor probably pulled down the project too. The group’s own foundry was dictating the price, quality and quantity of casting supplied. The foundry’s expectation was a price of $1.40 per kg of casting, which could otherwise be sourced from Taiwan at that time for $0.3 – 0.55 per kg in fully machined condition!
- Since all the previous years had gone without testing a single product, the accuracy and reliability of the equipment, tooling and people were not tested and established.
- Lead times for various activities were unknown. Operations were not standardized and throughput times were not known.
- The first few sample milling heads or initial requirements were to be purchased from the collaborator. The prices of these were not competitive and in fact, were exorbitant, thus making the product unsellable. The brand may have had its name, but knowledgeable customers knew cost effective sources for similar machines and their features. Why was the milling head design put into a delay phase of development? Confidence, lack of knowledge or the capability to process it?
- The opportunities in machining centers presented more excitement. Why was this on the next phase? Why was it not concurrent?
- What was the strategic intent of the local partner? What was the overriding philosophy? Was there intent to make this company profitable? Was it serious about the joint venture plans?
- The plant and equipment supplied by the collaborators were rebuilt machines; they were never put to test here and were never beaten for production. The capacity, capability and reliability of this line was not proven and established.
- The percentage market share of the collaborator was less than one half percent of the milling machines market. Where was the argument then about what the customers wanted?
- Did the owners have intent to flourish in this business?
It was clear that we had to think of ways to quickly establish the manufacturing, its supply chain, establish throughput times, lead times, and deal with cash cycles etc., all while contending with detractions from peers and discrete thinking within the group.
Formulating the strategy
The long-term objective was to develop a supply chain from within Indonesia and that would include our group companies – provided they were competitive. But in the short-term we had to address the market needs too. We had to develop reputation of being a reliable machine tool manufacturer and service provider. Considering the training and development time required within, we needed a strong short to medium-term strategy that could catapult us into the global markets and help understand the customer requirements and establish us as reliable suppliers. These strategies were:
Buy gears and castings from in-house group companies
We had to test ourselves to produce all components in house. Could we develop them all simultaneously? Were we geared up for it? The head was a critical assembly and had intricate component machining. Among the machinery installed, there was no machine available to finish machine high precision parts. The hardening facilities for the spindle were also not installed. A group company that had a gear shop could have been asked to supply gears, but they did not have proper equipment to produce gears of quality class IT-5 and 6. So in our assessment the factory was not ready to produce the ‘heads’ in-house. We had to either source the components or the assembly in the short to medium term.
The group foundry was ready to supply castings. They had received the patterns of parts other than the head from the collaborator and made some sample castings. Quality issues on casting prevailed but, these could be resolved and overcome. The foundry was selling the castings at $1.40 per kg and wanted to be the final authority on price and salvaging standards! These factors would render us uncompetitive in the global market and hence was not acceptable.
The advantage of building this assembly in house was obvious, and we wanted to get to this stage and bring in all that value addition. However, in the beginning our priorities included customers, markets, channel partners, supply chain partners, working capital, etc. Thus, in the beginning we were not equipped to produce everything in-house.
Source from points of cost advantage without sacrificing quality
Although cost-based strategy would have been the right approach, with the outsourcing thought the differentiation strategy may not hold out. We could source the parts or assemblies from India or Taiwan but this singular approach would not help develop internal competence.
Concurrent strategy
The critical issue was that even after five years since inception the joint venture had failed to produce machines, bag orders, establish markets, and corner a share in the market place. Everybody was eager to begin producing and delivering machines. The concurrent strategy was to set up two supply chains; one that focused on developing internal competence (long term), while the other supplied parts from Taiwan until such time we had developed competence to produce parts of the required quality in the required takt time. This would give us the following advantages and help overcome all the in-between problems:
- To start with, we would commence manufacture of all components other than the ‘milling head’, and work on perfecting the supply chain, procurement cost and quality, manufacturing processes, cycle times, lead times, throughput times, standardize work, develop the ability to solve problems, documentation etc. All that would ensure rapid flow of components.
- Initially we would not be constrained by the results of in-house processes for component manufacture – considering the used machines handed down by the collaborator, and whose process capability was not established or proven. But, could respond to the market demands and fulfill those using outsourced components.
- One of the dominant challenges was building in the core competencies, lean systems and processes required to succeed. This was our top priority. The outsourcing strategy was to gain time to build these competencies and yet not lose the present market, but to begin building a reputation and an image.
Bring in the machining centers & CNC milling machines
Our intent was not to lose out on present markets while quickly moving on to future ones. We knew that to gain a share of this market we had to compete with the Taiwanese manufacturers, besides with the exception of Singapore, South East Asian countries are not known to be machine tool producers. To make money in this market one had to produce at low costs and high volumes; however, the sales volumes and contributions could only improve by enriching the product mix. The collaborator had a range of CNC machining centers and CNC milling machines. The bigger opportunities, greater markets, and better contributions lay in these products.
Living the challenge
We knew what to buy and from where to gain that cost advantage. We challenged ourselves to buy components from Taiwan, on 30 days credit, build the machines, ship them, collect payment, and pay the supplier all in less than 30 days. Our negotiating skills brought a huge cost advantage, which looked something like:
Taiwan was the biggest seller of these machines; the challenge for us was to be more competitive than Taiwan even though we were sourcing from Taiwan! To give you a broad idea, the costs worked thus then:
If Taiwan sold a machine at $2,400-2,600, we couldn’t price ourselves over this as it would hinder the share acquisition from a country not known to produce machine tools. We had to be equal or be at a better notch at least at entry level. We challenged ourselves to sell at $2,200 - 2,300 a machine.
We bought complete raw material in fully machined and ready to assemble condition at $1,180 per set. With internal fixed costs, painting, packing and warranty at $350 per set, there was a clear surplus generated of $670 (or $770) per set. This meant that at 100 machines per month we would generate a surplus in excess of $800,000 (or $925,000) per year! This was targeting to take away a mere 3.5 per cent share from Taiwan. There was scope to take more market share and further consolidate revenues with the rest of the Bridgeport product range.
This was fantastic news for any factory that was struggling to produce its first machine for five years. Naturally as in house production of components took over, the contribution would only increase. The advantage of this strategy was in being able to start up manufacturing and delivering with short lead times, enabling to establish a network of dealers and build an image.
Possibility thinking
Another problem to overcome was the absence of working capital. We challenged ourselves to set this up without initial capital. All the while everything we did was tuned to the lean practices as best known to us. Our core team was motivated to believe that we could do this.
We carefully selected supply partners, agreed on lead times, quality and delivery. We placed annual orders and indicated initial pickoff quantities that would self-convert into demand rates later. One supplier was nodal to the shipment of everyone’s parts. We then picked a liner that best maintained schedules. It took seven days for the ship to dock in Jakarta, two days to receive the container at factory and two days to build the machines. So the machines were ready for delivery in fifteen days from parts’ shipment. We shipped the machines, encashed the letters of credit and paid our suppliers on the 30th day.
The victory
From all the alternatives discussed above the dual strategy action taken by us was perhaps the best. The ownership of the group and the management at first were divided on this issue. However we went ahead as it was in the best interest of the company and its stake holders. Enacting the dual concurrent strategy we quickly had the assembly and dispatch bays in the factory buzzing with activity. In about six months we had established channels around the world, booked firm orders, which were covered by order commitments for the next year and a half, received letters of credits for payments.
What made this transformation happen? Lean thinking! The multi culture of the work force was not an issue, even though they exhibited varied levels of resistance. As long as we were focused, thinking and acting lean, everything else fell into place.
Download the original PDF Turnarounds-with-lean-management.pdf
Download PDF ↓ Originally published in Modern Manufacturing India · July 2013
Keep reading
More on Lean Manufacturing
ARTICLE
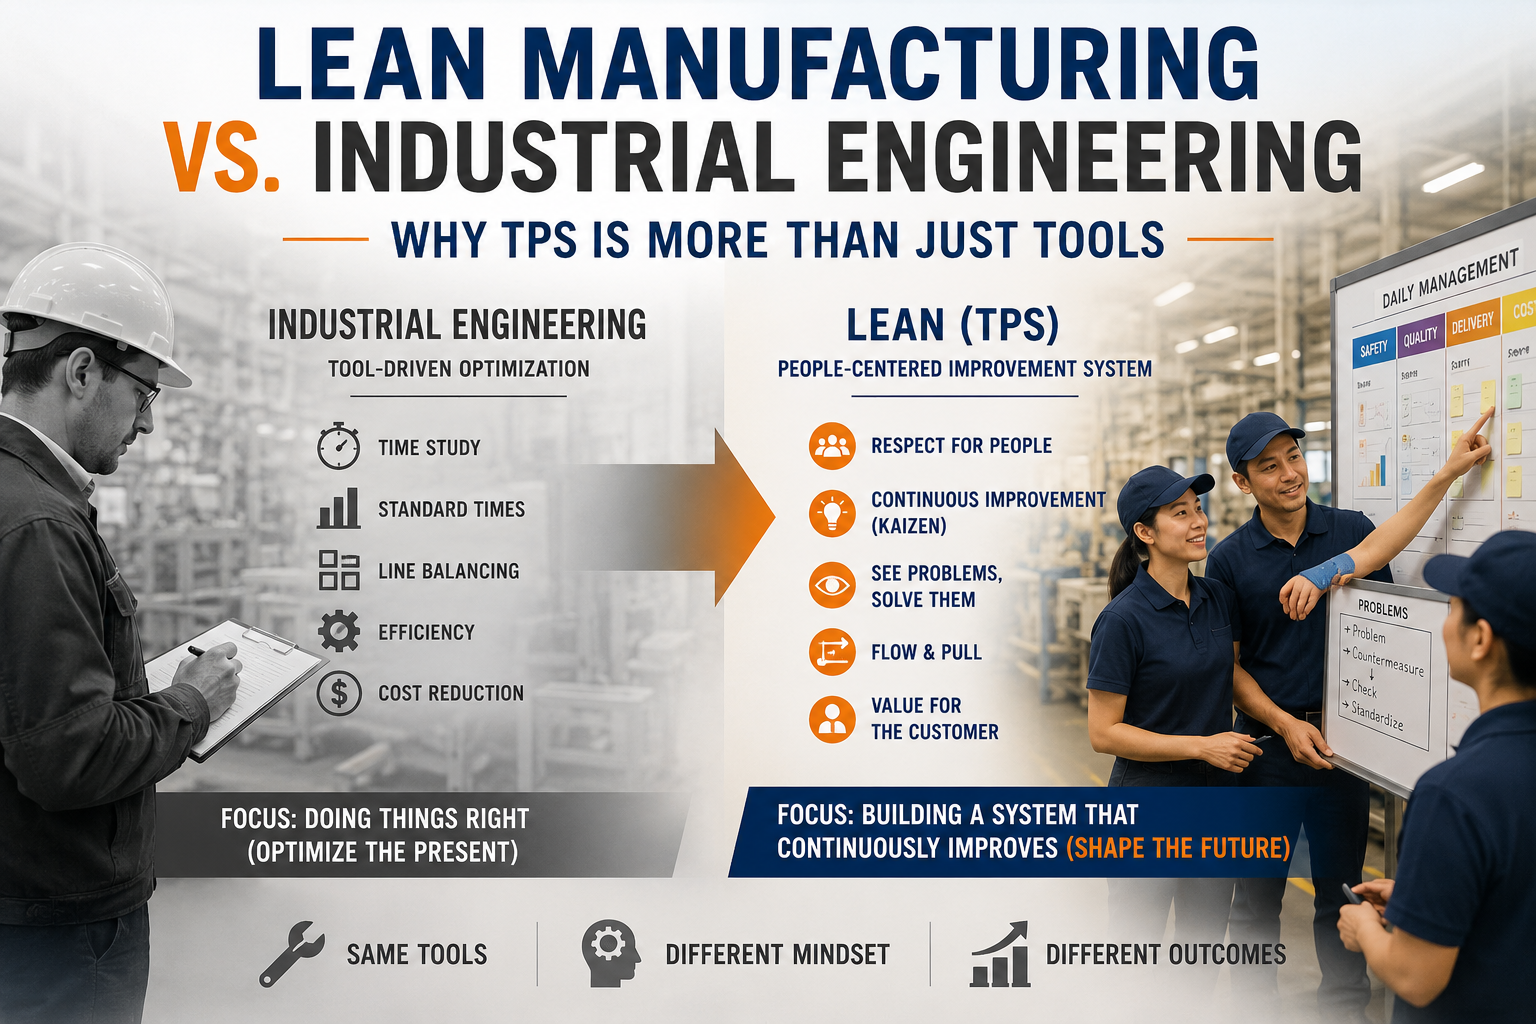
Lean Manufacturing vs. Industrial Engineering: Why TPS Is More Than a Toolkit
Lean ManufacturingMay 2026